Insurance claims and settlement negotiations in Colorado Springs involve evaluating an injury, determining responsibility, and seeking an agreement on compensation with the applicable insurance company.
The process applies to car accidents, motorcycle and truck crashes, falls, unsafe property conditions, and other personal injury matters.
Insurance adjusters review evidence of liability, medical expenses, lost income, and the available insurance coverage before responding to a settlement demand.
Springs Law Group represents personal injury clients in Colorado Springs and negotiates with insurers on their behalf.

An insurance claim is a formal request for payment under an applicable policy after an injury or covered loss.
Settlement negotiations are discussions between the injured person or their attorney and an insurer about the financial compensation needed to resolve that claim.
A claim against someone else’s liability insurer is generally a third-party claim, while a request for covered benefits under a person’s own policy is a first-party claim.
The distinction affects policy obligations, available benefits, and how disagreements with the insurer may be addressed.
A personal injury claim can involve medical bills, lost wages, physical pain, and future medical care, while the policy and circumstances determine which amounts an insurer may be required to pay.
If you suffered injuries because of another person’s negligence and are having difficulty obtaining a fair settlement, Springs Law Group can review the claim and the insurance company’s response.
Contact us for a free consultation or use the chat feature on this page to discuss your situation with a Colorado Springs personal injury attorney.
Most injury claims involve an investigation, a review of damages, a settlement demand, and negotiations over the amount and terms of payment.
The negotiation process may begin before medical care is complete, but serious injuries and unresolved treatment needs can make an early settlement difficult to assess accurately.
The claims process usually begins when the injured person, their attorney, or another involved party reports an accident to the appropriate insurer.
An insurance claims adjuster may review an accident report, a police report, photographs, witness statements, and the insurance policy to evaluate liability and coverage.
For a car crash, the insurer may also examine vehicle damage, repair estimates, and evidence concerning the drivers involved.
For an injury on someone else’s property, the investigation may instead involve photographs of the hazard, maintenance records, incident reports, or statements from employees and witnesses.
Claims adjusters can request additional records, speak with the people involved, and make a preliminary assessment of responsibility.
Accident victims should report claims promptly under applicable policy requirements and keep copies of letters, messages, and notes from phone calls.
Medical records help show the victim’s injuries, the medical treatments received, and how the condition has affected everyday activities.
An insurance adjuster may review emergency care, physical therapy, diagnostic imaging, treatment plans, and medical documentation supporting the need for ongoing treatment.
The insurer may also ask about medical history or try to find pre-existing conditions that it believes explain some of the symptoms.
A prior injury does not automatically prevent someone from seeking compensation for an accident-related aggravation, although the medical evidence must support the claimed connection.
Pay stubs, employer records, medical bills, and receipts help document lost wages, medical costs, and other financial losses.
When future medical needs remain uncertain, a physician’s prognosis or recommendations for further care can be important to assessing the claim.
Once liability and damages can be assessed reasonably, an attorney may submit a demand letter to the insurance company requesting a specific settlement amount.
A comprehensive demand letter detailing the accident, injuries, medical history relevant to the claim, and resulting financial losses gives the insurer a basis for evaluating the request.
The demand may include supporting evidence such as accident reports, medical records, wage statements, photographs, and estimates of future medical expenses.
It should distinguish documented immediate costs from reasonably supported future medical costs and reduced earning capacity.
The requested amount may also account for non-economic damages, including physical pain, emotional distress, and loss of enjoyment of life, when recoverable under the circumstances.
A demand is a negotiating position, not a guarantee that the insurance company will agree to pay the requested sum.
After evaluating the demand, the insurer may accept it, request additional information, dispute parts of the claim, or make an initial settlement offer.
An early settlement offer may address immediate medical bills or property damage without fully accounting for ongoing treatment, lost income, or future medical expenses.
Some initial offers are substantially lower than the amount requested, but a first offer is not automatically unreasonable simply because the parties disagree about value.
An insurer may contest expenses in an effort to minimize payouts, and a claimant can challenge the assessment with relevant documentation.
The insurance adjuster may question whether particular medical treatments were necessary, whether all symptoms resulted from the accident, or whether the injured person shares responsibility.
Many injury victims receive offers while they are still recovering, making it important to compare the settlement amount with the evidence of their current and future losses.
An offer can be accepted, rejected, or answered with a supported counteroffer.
During settlement negotiations, the attorney and insurance company may exchange offers, additional medical documentation, and explanations of disputed losses.
Presenting evidence of future medical needs, lost wages, permanent limitations, or overlooked treatment can strengthen the claimant’s negotiating position.
A lawyer may also respond when an adjuster disputes liability, relies on incomplete records, or proposes a figure that does not reflect documented damages.
The claim negotiation process can involve several phone calls and written counteroffers over weeks or months, depending on the injuries, number of parties, and complexity of the dispute.
Throughout the settlement process, the parties may revise their positions as new medical evidence or coverage information becomes available.
Negotiating with insurance companies does not require accepting the first number offered or agreeing to every condition the insurer proposes.
A fair settlement should be evaluated against the supported claim value, available coverage, potential legal defenses, and terms of the release.
When the parties agree on compensation, the insurer typically requires a signed settlement agreement or release before issuing payment.
Claim settlements can cover bodily injuries, property damage, or both, depending on the agreement.
The release may permanently resolve specified claims arising from the injury, even if the person later needs more medical care.
Medical liens, reimbursement obligations, case expenses, and attorney fees may need to be addressed before settlement funds are distributed.
When settlement negotiations fail, filing a personal injury lawsuit may allow the injured person to seek a court determination while continuing discussions about resolution.
Mediation may help the parties reach an agreement, and arbitration may be available where required by an applicable agreement or accepted by the parties.
A lawsuit does not guarantee a higher payment, and many cases resolve before trial even after litigation begins.
Insurance negotiations can arise whenever an injured person seeks payment under liability coverage or another applicable policy.
The evidence, responsible parties, and types of coverage differ across personal injury matters.
A Colorado Springs car accident may involve the other driver’s liability insurance and, in some cases, coverage under the injured person’s own policy.
A truck accident can involve a commercial policy, disputed responsibility between multiple parties, and serious injuries that require substantial future care.
In motorcycle accident claims, insurers may contest fault, the extent of injury, or the need for surgery and rehabilitation.
Damage to a vehicle, car repairs, or other property damage may be negotiated separately from compensation for bodily injuries.
Pedestrians struck by vehicles may have significant medical expenses and lost income even when there is little property damage to document.
Bicycle accident claims can involve damaged equipment, head or orthopedic injuries, and disputes about how the collision occurred.
Rideshare injury claims may require reviewing which insurance coverage applies to the driver and whether the driver was transporting a passenger or using the platform at the time.
The settlement evidence should address the injured person’s actual losses rather than relying only on vehicle repair costs or the visible damage from a crash.
In a slip-and-fall injury claim, an insurer may examine the property condition, incident reports, maintenance records, photographs, and evidence about notice of the hazard.
Other premises liability cases may involve falling objects, unsafe stairs, or injuries caused by inadequate property maintenance.
A property owner’s or business’s liability policy may be relevant, but coverage alone does not establish that the owner is legally responsible.
Medical bills, missed work, and documented long-term limitations can affect negotiations just as they do in vehicle accident claims.
Serious injuries such as traumatic brain damage, spinal cord injuries, or permanent disability can create claims involving future medical expenses, reduced earning capacity, and lifelong assistance.
In a catastrophic injury claim, expert assessments may be needed to estimate the cost of future medical care and changes to the injured person’s ability to work.
Wrongful death claims may involve negotiations over eligible family members’ legally recoverable losses and the available liability coverage.
The amounts and categories of recoverable damages depend on Colorado law and the particular claim.
Depending on the responsible party and the applicable policy, an injury claim may involve a national automobile insurer, a commercial carrier, or an insurer providing liability coverage to a property owner or business.
Insurance companies associated with injury claims in Colorado Springs include:
The insurance company involved does not determine the value of a personal injury claim on its own.
Liability, the policy language, coverage limits, the evidence, and the injured person’s losses are more important to the settlement calculation than the name of the insurer.
The same company may handle a first-party claim under a person’s own policy and a third-party claim against someone it insures, with different legal obligations in each situation.
Several issues can change an insurer’s assessment of a personal injury claim or the amount the parties are willing to accept.
An insurance company may argue that the injured person caused the accident or shares responsibility for the injuries.
Colorado’s comparative negligence law generally reduces recoverable negligence damages in proportion to the claimant’s fault and can bar recovery when the statutory threshold is met.
In claims involving a car crash, a police report, witness statements, video, and photographs may help resolve conflicting accounts.
For an injury on another person’s property, maintenance records, incident reports, and the circumstances of the hazard may be more important.
A disputed fault percentage can significantly change a settlement offer even when both parties agree about the cost of medical care.
The amount available from a particular policy can affect settlement negotiations even when documented losses are higher than the available limits.
A third-party liability claim seeks compensation through coverage held by the person or business alleged to be responsible, subject to the policy and legal defenses.
A first-party claim may involve benefits owed under the injured person’s own insurance, such as uninsured or underinsured motorist coverage after a qualifying motor vehicle accident.
The distinction matters because Colorado law addressing unreasonable delay or denial of first-party benefits does not treat every person claiming against someone else’s liability policy as a first-party claimant.
When an insurer refuses to pay benefits allegedly owed under its own policy, legal representation involving an insurance claim dispute may require separate analysis of coverage and claim handling.
Economic damages can include past medical expenses, lost wages, and other measurable financial losses related to the injury.
Future medical costs and reduced earning capacity may also matter when supported by medical opinions, employment records, and reasonably reliable estimates.
Non-economic damages involve losses such as physical pain, emotional distress, and reduced enjoyment of life, subject to applicable Colorado law.
An insurer may disagree with the need for ongoing treatment, question whether future care is likely, or challenge expenses attributed to pre-existing conditions.
Medical records and treatment plans can help separate the immediate costs from long-term losses rather than relying on a simple multiplier to set the settlement amount.
Punitive damages serve a different purpose: Colorado permits exemplary damages only in circumstances meeting specific statutory requirements, not as an automatic addition to an ordinary insurance settlement.
An insurance company may reject a demand because of disputed liability, an exclusion, missing evidence, or disagreement about the extent of the injuries.
Other disagreements involve repeated requests for documents, unexplained delays, or settlement offers that do not address supported expenses and losses.
A claimant should distinguish legitimate requests for information from delay tactics intended to postpone a decision or payment.
Under Colorado’s unfair claim settlement practices law, specified insurer practices can be unlawful, including certain failures to investigate reasonably, respond to communications, or explain denials.
A low offer or difficult negotiation does not by itself establish bad faith, and not every insurance dispute provides a separate claim against the insurer.
Keep correspondence, the insurer’s written reasons, records of phone calls, and copies of any new evidence submitted in response.
If a claimant believes they have not been treated fairly, the written explanations and claim history can help determine what happened.
When the insurance company refuses to make an acceptable offer, an experienced attorney can assess whether further negotiations, mediation, or a personal injury lawsuit would be appropriate.
People facing an unexplained denial or approaching deadline should seek legal advice before making a final decision.
Springs Law Group represents people seeking compensation after motor vehicle accidents, unsafe property conditions, and other injury-causing incidents throughout Colorado Springs and El Paso County.
The firm’s attorneys gather medical records, document financial losses, evaluate available insurance coverage, and negotiate with insurers when a settlement is supported by the evidence.
In one Colorado Springs motorcycle accident case, Springs Law Group secured a $1.5 million settlement after an initial insurance offer of $735,771; the client had suffered serious injuries requiring multiple surgeries.
In a separate slip-and-fall case, the firm recovered $130,000 after an initial offer of $50,000 for a client who needed surgery following a fall on a poorly lit staircase.
Past settlement results do not predict the outcome of another injury claim.
Legal representation can help injured people challenge unsupported valuations, present evidence of future losses, and avoid costly mistakes when reviewing a proposed settlement.
Springs Law Group handles qualifying personal injury claims on a contingency fee basis, with attorney fees and case expenses explained in the written agreement.
If you suffered injuries because of another person’s negligence, contact Springs Law Group for a free consultation or use the chat feature on this page to discuss your insurance claim and whether you can seek compensation for your losses.
Not before reviewing whether the offer reasonably accounts for the injuries, medical bills, lost income, and future needs supported by the evidence.
An initial settlement offer may arrive before treatment is complete and may not include all recoverable losses.
Accepting a settlement and signing a final release can prevent further recovery for claims covered by that agreement, even if new expenses arise later.
Yes, a person can handle an insurance claim and respond to an adjuster’s settlement offer without hiring a lawyer.
However, claims involving serious injuries, disputed liability, pre-existing conditions, or future medical needs can be harder to value and negotiate.
An injured person may try to save money by handling the claim alone, but should weigh that decision against the possible consequences of an inadequate settlement and the terms of any legal representation agreement.
There is no reliable basis to promise that hiring personal injury lawyers will produce a larger net settlement in every case.
Some accident claims resolve after a few exchanges, while others take months or longer because of disputed facts, ongoing medical care, or disagreements over coverage.
Settlement negotiations may continue after a personal injury lawsuit is filed, and mediation may create another opportunity for agreement.
There is no fixed schedule that applies to every claim settlement.
An injured person may present evidence correcting the insurer’s assessment, submit a supported counteroffer, or obtain legal advice about filing a lawsuit before the applicable deadline.
If the disagreement concerns benefits owed under the claimant’s own policy, the policy language and Colorado’s first-party insurance rules may raise additional issues.
An insurer’s refusal to accept a particular settlement amount does not automatically establish an unlawful denial.
Public social media posts may become evidence if they contain information relevant to the accident, physical activities, or reported limitations.
An insurance adjuster may compare a claimant’s statements with medical documentation or other available information, but that does not mean every insurer monitors every account.
Preserve relevant information and avoid making misleading statements about your injuries or recovery.
Yes, a person does not always need to complete every appointment or reach maximum medical improvement before settling.
However, ongoing treatment and uncertain future medical expenses make it important to assess the full expected cost of care before signing a release.
Medical opinions about recovery, rehabilitation, and permanent limitations can help establish a reasonable negotiating position.
The injured person may consider filing a lawsuit against the legally responsible party, depending on the type of case, evidence, and applicable deadline.
Negotiations may continue during discovery, mediation, or trial preparation, and some disputes may proceed to arbitration when an agreement or policy provides for it.
A lawsuit does not guarantee maximum compensation, and any settlement should be considered in light of the claim’s evidence, risks, and available coverage.
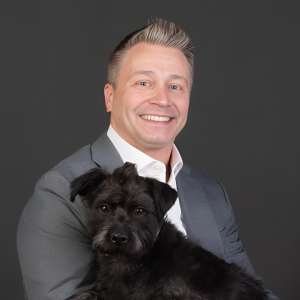
Member of the Colorado Bar Association since 2014. Attorney, Christopher M. Nicolaysen focuses primarily on helping those injured in Colorado car accidents, other auto accidents, and Colorado personal injury incidents.
This article has been written and reviewed for legal accuracy and clarity by the team of writers and attorneys at Springs Law Group and is as accurate as possible. This content should not be taken as legal advice from an attorney. If you would like to learn more about our owner and experienced Colorado personal injury lawyer, Christopher Nicolaysen, you can do so here.
Springs Law Group does everything possible to make sure the information in this article is up to date and accurate. If you need specific legal advice about your case, contact us. This article should not be taken as advice from an attorney.
We use reviews to help show more people like you why we do what we do!
I was uneasy about reaching out to a law firm after being in an accident that left me injured and my vehicle totaled. I don’t care for the idea of suing for what was very clearly an accident. However, after learning more about the overall process of working with a professional team to navigate the murky waters of the insurance world, I was pleasantly surprised to find that the experience wasn’t as gross as I’d originally felt about it.
Springs Law is very friendly and professional. I always felt that they were on my side and cared about my injury and what I was going through. I highly recommend them.
Springs Law Group is an amazing group to work with! I got into a rough accident, and they never ceased to let me know they were there working hard to help me in my hour of need. It was always very easy to reach out to someone if I had any questions, and they were always happy to answer any questions I had.
I never have a problem with getting a response when I need them – which is not the case with most other firms. They really truly care about each client. As a plus, they always have positive attitudes, which matters tremendously when you are in a stressful legal situation.
Big thanks to Mr. Jake Kimbell and his team for their assistance with my case. He helped me through an incredibly challenging part of my life, and most importantly helped navigate through the convoluted legal channels of my case. I cannot thank him and his team enough for their support.
The entire team at Springs Law group has been nothing but amazing. Jake and the rest of the staff were great to work with and extremely professional. They were very attentive and answered any questions and concerns I had. I was always able to contact them and they were very responsive and communicated with me.
Springs Law Group is an amazing group to work with! I got into a rough accident, and they never ceased to let me know they were there working hard to help me in my hour of need. It was always very easy to reach out to someone if I had any questions, and they were always happy to answer any questions I had.